
A routine fender bender once meant a simple repair, a short rental, and a resolved insurance claim. Today, that same minor collision frequently results in a total loss designation. This shift is driven by a double threat: lingering global supply chain disruptions and the rising complexity of modern vehicle safety features.
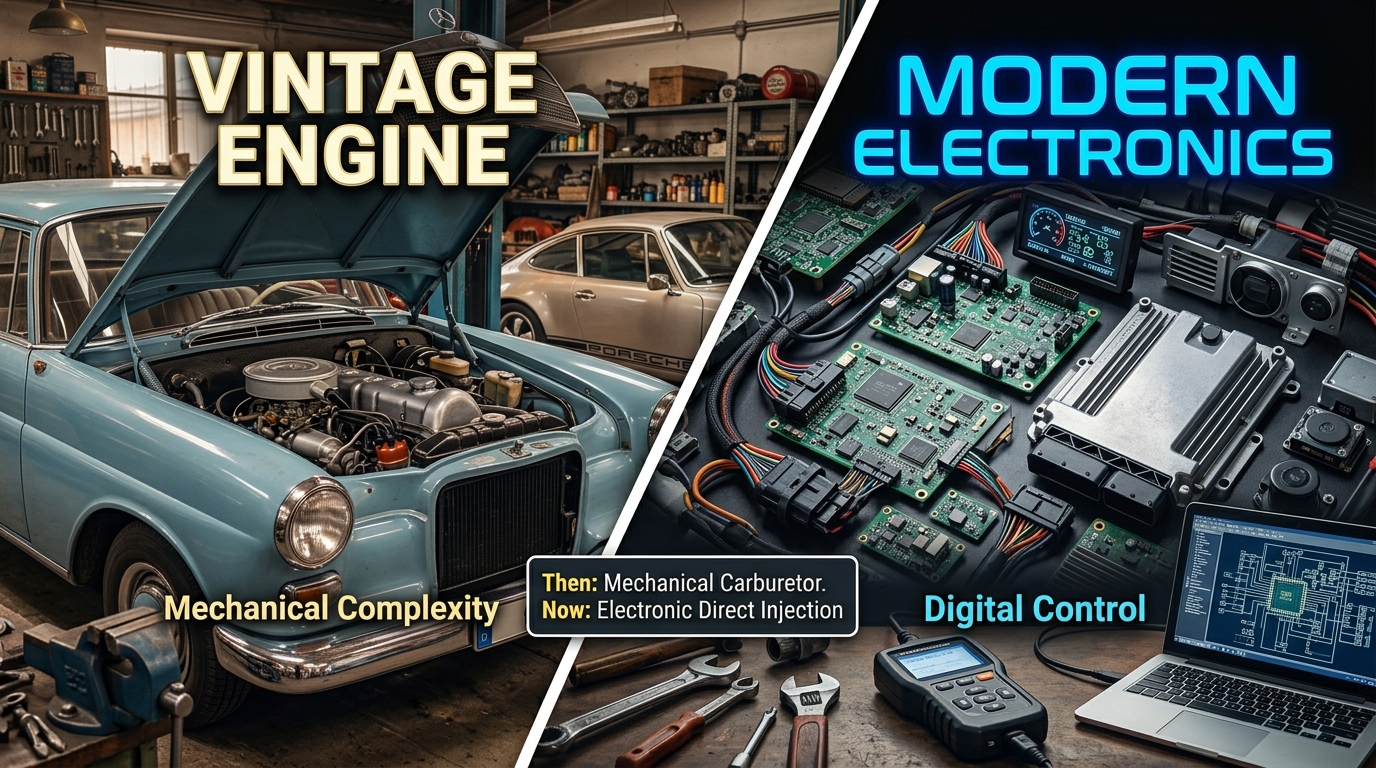
Modern bumpers and windshields no longer contain just plastic and glass—they house advanced driver assistance systems (ADAS) such as radar sensors, cameras, and air bag modules. A single damaged LED headlight can exceed $1,000, while specialized ADAS recalibrations and rising labor costs push repair bills past economic thresholds. Coupled with scarce replacement parts and extended rental car delays, repair costs routinely eclipse actual cash value, forcing insurers to write off otherwise fixable cars.
This "total loss" trend leaves vehicle owners facing negative loan equity, forces repair shops to lose valuable service revenue, and contributes to rising auto insurance premiums across the industry. To mitigate risk, drivers should regularly review policy limits, consider Gap insurance for financed vehicles, and maintain detailed records of vehicle maintenance to negotiate fair actual cash value settlements.